Alexander Rivera
Stamp duties can add a significant sum to the cost of a home, and the terminology is dense. Rates, thresholds and rules are set by the authorities and have been revised several times, so this glossary explains what each duty is for rather than quoting figures. Always check the latest numbers with IRAS before you budget.
The Core Duties
Buyer’s Stamp Duty (BSD). This is paid by every buyer of residential property in Singapore. It is calculated on the purchase price or market value, whichever is higher, and it is tiered, meaning different slices of the price are taxed at different rates. A higher-priced home therefore attracts a progressively larger share of duty on the upper portion.
Additional Buyer’s Stamp Duty (ABSD). This is an extra layer that depends on who you are and how many properties you own. Citizens, permanent residents, foreigners and entities are treated differently, and the rate generally rises with the number of residential properties held. Its purpose is to cool demand and discourage speculation. If you are upgrading and still own another home, ABSD is the item most likely to change your plans.
Seller’s Stamp Duty (SSD). This applies when a property is sold within a set holding period after purchase. It is aimed at short-term flipping. If you expect to sell early, it is worth knowing how the holding window is counted.
Terms That Often Cause Confusion
Remission and refund. In some situations, ABSD can be remitted or refunded if specific conditions are met, such as selling an existing property within a stated period. Those conditions differ by buyer profile and property type, and the deadlines are strict. Missing one can be costly.
Market value versus price paid. If the agreed price is lower than the assessed market value, the duty may be based on the higher figure. This matters mainly in related-party transactions.
Timing of payment. For resale homes, duty is payable within a short window after the agreement. For uncompleted private homes, the timing follows the contract’s structure, and your lawyer will explain when payment is due.
Budgeting for Duties
Many first-time buyers treat duties as an afterthought, then discover that the cash needed upfront is larger than expected. Some duties may be payable in cash rather than from CPF, depending on the circumstances. A sensible habit is to add stamp duties, legal fees, valuation fees and renovation costs to your budget from the start, and to keep a buffer.
A simple checklist:
- Estimate BSD using IRAS’s online calculator.
- Check whether ABSD applies to your situation.
- Note any selling deadlines tied to remission.
- Confirm which costs need cash.
- Keep a reserve for fees you did not anticipate.
Seeing the Duties in Context
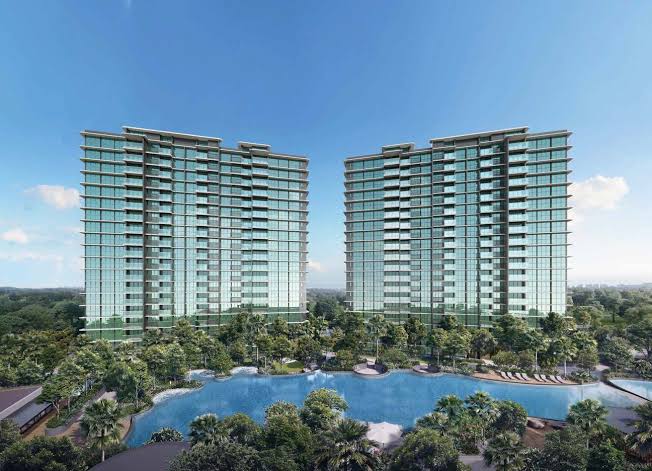
Websites for new launches often include a page on stamp duty for exactly this reason. The site for Chencharu Central Residences, a planned mixed-use condominium in Yishun, has a dedicated stamp duty section alongside its payment scheme and loan information. With pricing and launch timing still to be announced, it is best used as a starting point for conversations with the sales team and your own advisers rather than as a final calculation.
An executive condominium follows a different path. The planned low-rise project on Sembawang Road, marketed as Fablewoode Residences, would be bought under HDB eligibility conditions, and the duties that apply to ECs can differ from those for private condos, particularly for citizens buying their first home. Because the official name, price and launch details are not confirmed, any buyer interested should clarify the duties that apply to their situation directly with HDB, IRAS and a lawyer.
Common Mistakes
- Using outdated rates. Measures change, and old articles may be wrong.
- Forgetting ABSD triggers. Owning another property, even partly, can matter.
- Ignoring deadlines. Remission windows are fixed.
- Assuming CPF covers everything. Some payments need cash.
- Skipping professional advice. A conveyancing lawyer can flag issues early.
The Takeaway
Stamp duties are not mysterious once you know what each one is meant to do. BSD applies to everyone, ABSD depends on your profile and holdings, and SSD discourages quick resales. Learn which apply to you, use the official calculators and confirm every figure with IRAS before you commit. A few hours of preparation can prevent a costly surprise at the signing table.